An Unbiased View of Kam Financial & Realty, Inc.
Table of ContentsKam Financial & Realty, Inc. - An OverviewThe 30-Second Trick For Kam Financial & Realty, Inc.Kam Financial & Realty, Inc. Can Be Fun For EveryoneThe Only Guide to Kam Financial & Realty, Inc.The Definitive Guide to Kam Financial & Realty, Inc.Some Known Details About Kam Financial & Realty, Inc. Kam Financial & Realty, Inc. - TruthsSome Known Details About Kam Financial & Realty, Inc.
If your neighborhood region tax price is 1%, you'll be billed a residential or commercial property tax obligation of $1,400 per yearor a month-to-month property tax obligation of $116. . We're on the last leg of PITI: insurance coverage. Look, everyone that purchases a house requires home owner's insuranceno ifs, ands, or buts regarding it. That's not necessarily a bad point.Keep in mind that nice, fancy escrow account you had with your building tax obligations? As with your building tax obligations, you'll pay component of your homeowner's insurance premium on top of your principal and rate of interest payment. Your lending institution gathers those repayments in an account, and at the end of the year, your insurance company will draw all that money when your insurance policy repayment is due.
Kam Financial & Realty, Inc. - Questions
It's implied to protect the lender from youwell, at the very least from the opportunity that you can not, or just flat don't, make your home mortgage payments. Of course, that would certainly never ever be youbut the lending institution doesn't care. If your down payment is much less than 20% of the home's price, you're going to obtain penalized PMI.
If you belong to a neighborhood like one of these, do not ignore your HOA charge. Depending on the age and dimension of your residence and the amenities, this could add anywhere from $50$350 to the quantity you pay each month for your overall housing prices. There are many kinds of home mortgages and they all charge various month-to-month repayment amounts.
Kam Financial & Realty, Inc. for Beginners
Since you intend to obtain a home mortgage the wise method, get in touch with our good friends at Churchill Home loan - mortgage lenders in california. They'll stroll with you every step of YOURURL.com the means to put you on the ideal path to homeownership
The Only Guide for Kam Financial & Realty, Inc.
This is the most typical type of home loan. You can take a table funding with a set rate of interest or a floating rate.
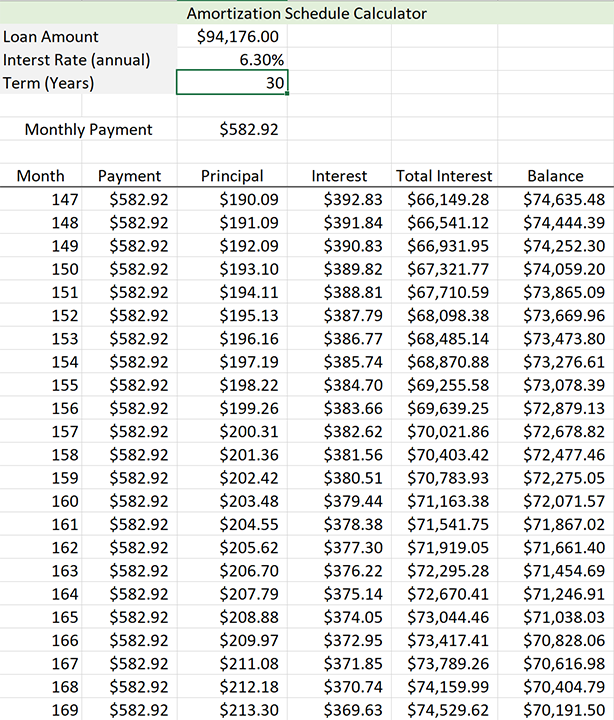
A lot of lending institutions charge around $200 to $400. This is frequently negotiable. california loan officer.: Table finances give the technique of normal repayments and a collection date when they will be paid off. They offer the certainty of understanding what your repayments will be, unless you have a floating price, in which situation repayment quantities can change
What Does Kam Financial & Realty, Inc. Mean?
Rotating credit scores car loans work like a large overdraft account. By maintaining the financing as low as feasible at any type of time, you pay much less rate of interest because lending institutions calculate rate of interest daily.
Application costs on revolving credit history home mortgage can be up to $500. There can be a charge for the everyday banking purchases you do through the account.: If you're well ordered, you can repay your home loan faster. This also matches individuals with unequal revenue as there are no fixed payments.
Kam Financial & Realty, Inc. for Dummies
Subtract the savings from the overall loan quantity, and you only pay interest on what's left. The more money you maintain across your accounts daily, the much more you'll conserve, since rate of interest is computed daily. Connecting as many accounts as possible whether from a companion, parents, or various other relative suggests also much less passion to pay.

The Ultimate Guide To Kam Financial & Realty, Inc.
Settlements start high, but minimize (in a straight line) gradually. Charges are similar to table loans.: We pay much less interest generally than with a table funding due to the fact that early repayments consist of a greater repayment of principal. These may fit consumers who expect their earnings to go down, as an example, if one companion strategies to provide up job in a few years' time.
We pay the interest-only part of our payments, not the principal, so the payments are reduced. Some borrowers take an interest-only car loan for a year or 2 and after that change to a table finance. The regular table loan application fees apply.: We have much more cash money for other things, such as remodellings.
Not known Facts About Kam Financial & Realty, Inc.
We will still owe the complete amount that we borrowed till the interest-only duration ends and we start repaying the car loan.
The mortgage note is generally videotaped in the public documents in addition to the home loan or the act of count on and offers as proof of the lien on the residential property. The home loan note and the mortgage or deed of depend on are two various records, and they both serve various legal purposes.